
Van finance for your working day
Before comparing payments, decide who needs the van, how it will be used and whether you want to keep it at the end.
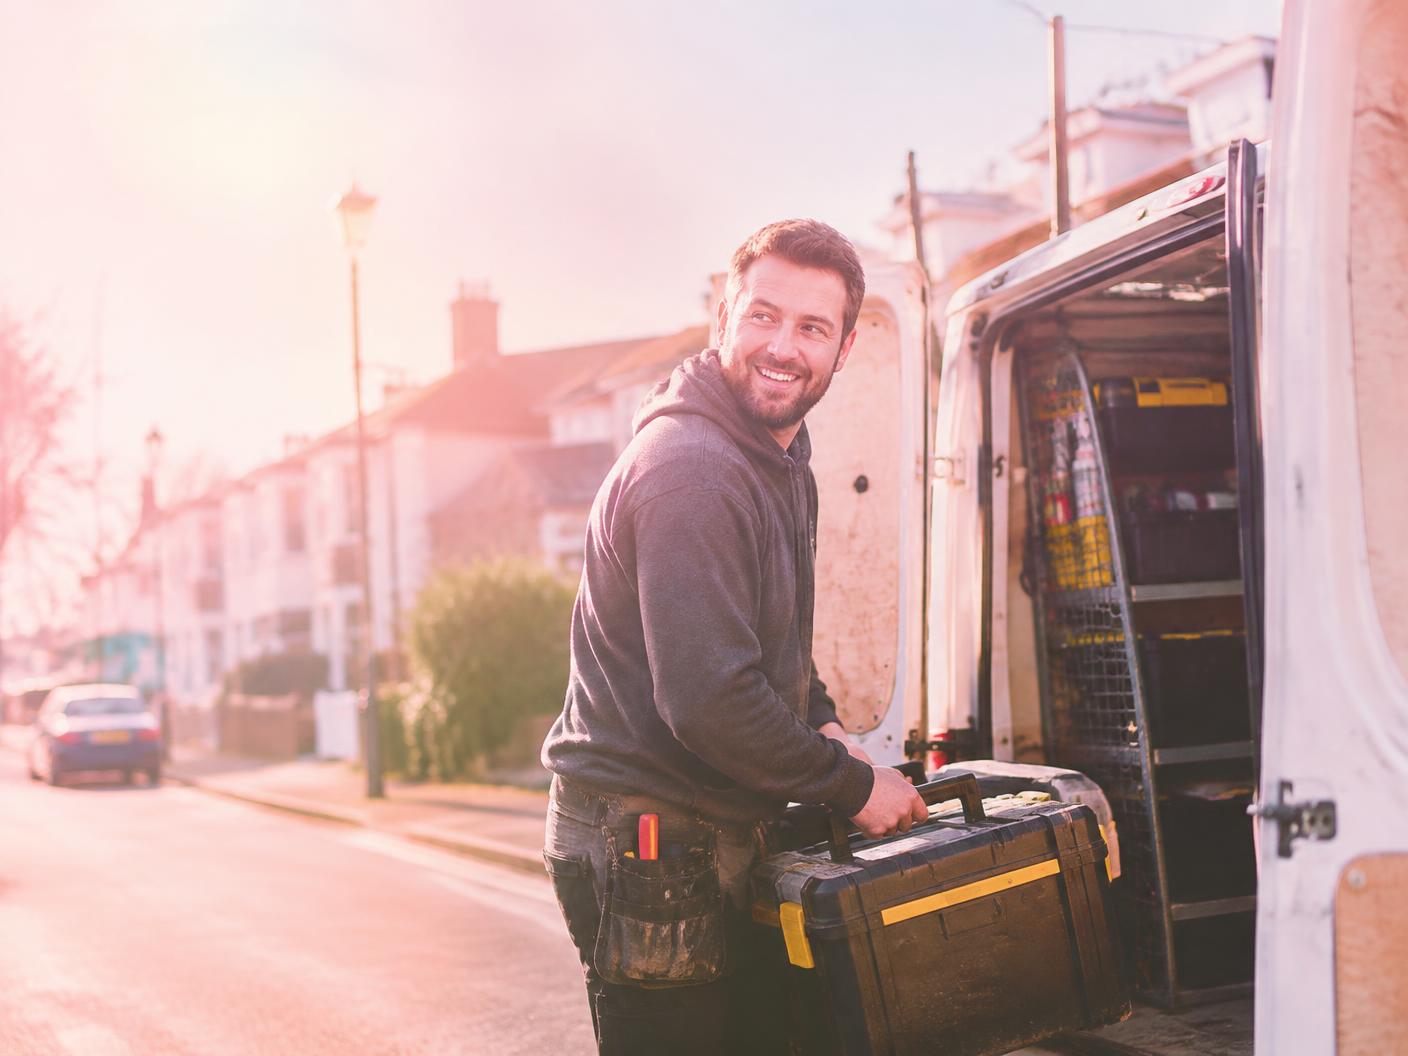
How does van finance work?
Van finance spreads the cost of a light commercial vehicle through hire purchase, a finance lease or contract hire. Sole traders and small firms often use it to keep cash for the business. Which agreement suits depends on whether you want to own the van, how you account for VAT and how long you will keep it.
♥ Quick answer
Van finance works much like car finance, but more applicants are self-employed or trading as a business, so evidence of income and trading history matter. HP leads to ownership; leases do not. VAT and tax treatment differ by agreement, so check them with your accountant before choosing.
What a dealer or lender will ask you
A commercial vehicle dealer will usually ask whether the van is for personal or business use, whether you are a sole trader or a limited company, and how long you have been trading.
Lenders typically ask for accounts, tax returns or bank statements to evidence income. A short trading history can mean a larger deposit is needed, though every lender sets its own criteria.
Buyers often focus on the van and forget the finance structure. Ask whether the quote is HP or a lease, how VAT is handled and what happens at the end of the term.
A worked illustration
- 1Van price £20,000, deposit £4,000, so £16,000 is borrowed over 60 months.
- 2Assume, for illustration only, £4,000 of interest and fees.
- 3£20,000 ÷ 60 = about £333 a month.
- 4VAT treatment depends on your business, so check with your accountant before relying on these figures.
Illustrative only, not a quote. Round numbers and an assumed interest figure are used to show the arithmetic.
How does it compare with contract hire?
| This option | Contract hire | |
|---|---|---|
| Ownership | Yes, on HP after the final payment | No |
| VAT and tax treatment | Ask your accountant | Ask your accountant |
| Mileage terms | None on HP | Agreed allowance |
| Best when | You keep vans for years | You replace vans regularly |
Read more about contract hire →
General information, not advice. Lenders set their own criteria and no outcome is implied.
A van's job matters as much as its price. Write down expected mileage, payload, any conversion and whether it will carry your own tools or make deliveries for others. Check the proposed agreement's permitted use and end-of-term conditions. If you're buying through a business, ask your accountant how ownership, VAT and tax treatment apply to your circumstances; this page is not tax advice.
Worth exploring if
- Drivers comparing private and work use before choosing an agreement
- Sole traders planning for variable mileage or seasonal work
- Companies deciding who will sign and how the van will be used
- People choosing between a route to ownership and a return at the end
What may suit you
- Explore ownership and return options before focusing on a monthly figure
- Check mileage, wear and end-of-term requirements against your real use
- Ask about the checks and documents involved
- Get independent tax advice for business use and VAT questions
Things to consider
- Vehicle weight, modifications and permitted use may limit available agreements
- Business prices may be shown excluding VAT — confirm what you would actually pay
- Conversions may require additional documentation or insurance checks
How van finance works
Who signs the agreement?
Decide whether it is a personal or company enquiry; this affects the documents and questions to prepare.
Map the working day
Record typical mileage, load, any conversion and the class of insurance use you will need.
Look at the last day
Compare the path to ownership under HP with any PCP final payment or hire return conditions.
In short
Van finance is available to sole traders, limited companies and private buyers, usually as hire purchase so the van is yours at the end. Business agreements can bring VAT and capital allowance advantages, and lenders assess trading history or personal affordability depending on how you apply.
- Common products
- HP, business contract hire, finance lease
- Who can apply
- Sole traders, limited companies, partnerships, private buyers
- VAT
- Often reclaimable on business use — check with your accountant
- Typical term
- 24 to 60 months
- Mileage
- No cap on HP; capped on contract hire
01
Which van finance product should I choose?
For most trades, hire purchase is the straightforward answer. You pay the van off over a fixed term, there is no mileage limit and no condition inspection, and the van becomes a business asset you own. That matters when a van is a working tool that will be loaded, racked out and driven hard.
Contract hire is the alternative if you would rather treat the van as a monthly cost and hand it back. Payments are usually lower, maintenance can be bundled, and there is nothing to sell at the end — but mileage limits and damage recharges apply, and heavy commercial use is exactly where those charges bite.
| Product | Own it at the end? | Mileage limit | Best for |
|---|---|---|---|
| Hire purchase | Yes | None | Trades keeping vans long term |
| Finance lease | Usually sale at the end | None | Businesses wanting flexibility and VAT treatment |
| Business contract hire | No | Yes | Fleets wanting fixed cost and no disposal |
02
What do lenders need from a business?
The paperwork depends on how you trade. A limited company with two or more years of filed accounts is the simplest case — the lender assesses the company and often asks for a personal guarantee from a director. Sole traders are assessed much more like private applicants, with bank statements and personal credit history doing the heavy lifting.
- Proof of trading — accounts, bank statements or invoices depending on structure
- Three months of business bank statements is a common request
- Details of the van, including whether it is being converted or racked out
- Address and trading history that matches the records
- For new businesses, a deposit or director's guarantee strengthens the case
03
What does van finance cost?
Van running costs behave differently from cars. Commercial insurance, goods-in-transit cover, higher tyre and brake wear, and more frequent servicing intervals all sit on top of the finance. Build them into the monthly figure before you decide what you can afford, and remember that a van standing idle after a breakdown costs income as well as repair money.
- 1
Decide own or hand back
This choice determines whether HP, lease or contract hire is right.
- 2
Talk to your accountant about VAT
Treatment differs by product and by how much private use there is.
- 3
Gather your trading paperwork
Bank statements and accounts speed up underwriting considerably.
- 4
Ask about eligibility
Ask about possible terms and the checks involved.
04
Can I finance a van for private use?
Yes. Plenty of people buy vans as personal vehicles — for camper conversions, motorsport, dogs or simply space — and personal hire purchase covers that. The application is assessed exactly like car finance: income, credit history and affordability. What you lose is the VAT and capital allowance treatment that applies to genuine business use.
If you are planning a conversion, tell the lender. A van being converted to a camper changes the vehicle's classification, insurance and value, and lenders vary in how they handle it. Being upfront avoids problems later in the agreement.
05
How do I choose the right van for the work?
The cheapest van to finance is not always the cheapest to run. Before comparing monthly figures, get clear on what the van actually needs to do day to day.
- Payload: the weight you carry, including tools, racking and passengers. Overloading is illegal and wears the van fast.
- Load length and height: measure your longest regular item and check whether you need a high roof.
- Daily miles and routes: lots of city driving and clean-air zones may change the right engine choice.
- Towing: check the braked towing limit if you pull a trailer.
- Racking and conversions: find out whether fitting them affects the finance or the van's value.
Writing these down before you start makes it much easier to spot a van that looks like a bargain but will cost you later.
06
What paperwork helps with van finance?
Van finance often supports people whose income looks different from a standard payslip. That is fine — it just helps to have the right evidence ready.
- Photo ID and proof of address covering recent years.
- If employed: recent payslips and bank statements.
- If self-employed or a sole trader: tax calculations or tax-year overviews, and business bank statements.
- If a limited company: recent accounts and the company's details, as the agreement may be in the business name.
- Details of any existing vehicle finance you plan to settle or keep.
07
What should I ask before signing van finance?
- What is the total amount payable, and is the price shown with or without VAT?
- Is there a balloon payment at the end, and what happens if I cannot pay it?
- Are there mileage or condition limits on this agreement?
- What would it cost to settle early if the business changes?
- Who arranges insurance, and does the van need business-use cover?
- How is the broker or dealer paid for arranging this finance?
If the van is essential to your income, think about what would happen if it was off the road for a week. Breakdown cover and a plan for repairs are worth budgeting alongside the monthly payment.
Common mistakes to avoid
Choosing contract hire for a heavy-use trade van
If the van will carry tools and take knocks, HP avoids end-of-contract damage recharges.
Budgeting only for the finance payment
Commercial insurance, servicing and tyres are materially higher on vans than cars.
Assuming VAT is always reclaimable
Treatment depends on business use and the finance product. Confirm with your accountant first.
Not declaring a planned conversion
Tell the lender up front — conversions affect classification, value and insurance.
Applying to several lenders while shopping around
Ask which searches may apply before making multiple applications.
Sources and review
- GOV.UK — Reclaim VAT on vehicles
- Financial Conduct Authority — Car finance — consumer information
- BVRLA — Commercial vehicle leasing guidance
Editorial review date: 5 August 2026. Figures on this page are illustrative and are not a personalised quote.
Using a van for work? Tell your insurer what it carries and how it will be used. Carriage of your own goods, delivery work and other uses can need different cover. Confirm cover directly before driving.
Our insurance partnerVan finance FAQs
Ready to find a finance route that fits?
Start with your plans and speak to a real person before deciding what comes next.
Real people available to help.